
MIDO 2027 Registration Opens as Italian Eyewear Absorbs a Tough First Half - Europe Holds, America Doesn't
leeyewear
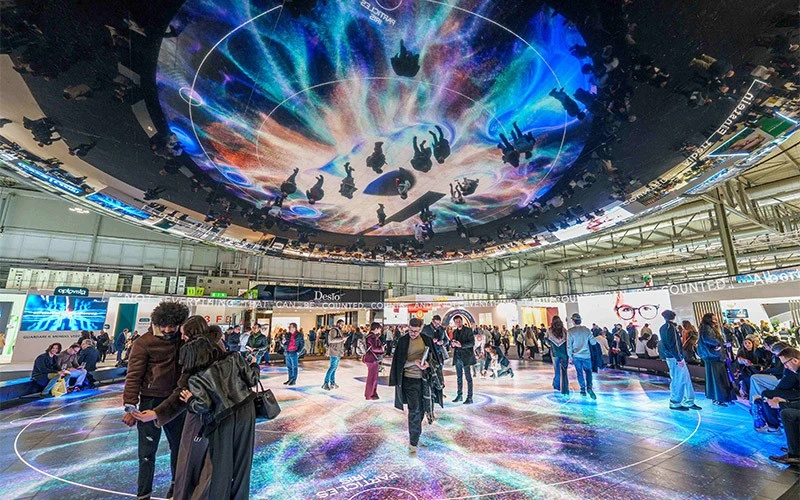
Registration for MIDO 2027 opened on 25 September, for visitors and for the press. The show runs 6–8 February 2027 at Fiera Milano Rho, and the early signs point to a busy edition: most of last year's exhibitors are coming back, new names are joining, and the whole eyewear chain - frame and lens makers, machinery, designers, opticians, buyers - will again be under one roof. Visitor passes are already live at mido.com/en/entry-pass, and press accreditation at mido.com/en/press-registration.
MIDO president Lorraine Berton sounds relaxed about it. "The response from exhibitors has been very positive," she said. After more than fifty editions, the show can afford a little confidence.
Two dedicated areas, Academy and Start Up, will once again host the younger end of the business. The Vision Stage - a MIDO institution for over twenty years - moves into Pavilion 1 with roughly twenty sessions across the three days, covering design, retail, health and everything in between. And for those who like their trade fairs with a bit of city attached, My Fair Plus, the new digital platform from Fondazione Fiera Milano, will point visitors toward exhibitions, performances and some very good food once the halls close. Travel deals are on offer for visitors from the US, Canada and Latin America, and this year also for visitors flying in from Wenzhou, Shenzhen and Shanghai.
The data released alongside the registration announcement is less cheerful. ANFAO's half-year figures put Italian eyewear exports - frames, sunglasses and lenses - at just over €2.7 billion, down 2.7% on the first half of 2025. Sunglasses took the harder knock: roughly €1.81 billion, off 3.7%. Frames held up far better, at about €830 million and down only 1.1%. Lenses, the smallest piece of the pie, actually grew, up 6.0% to around €68 million. Imports climbed 7.4% to some €982 million, which still leaves the industry with a surplus above €1.7 billion. Nobody at ANFAO is talking about a crisis. But nobody there is using the word "growth" either.
Look month by month, though, and the bruises start to fade. January was ugly - exports down 14.3% - but the hole kept shrinking: −2.6% in February, −1.9% in March, then April flipped positive at +3.0%. June closed at +3.7%, with both frames and sunglasses up on the same month a year earlier. ANFAO reads this as a gradual recovery, while carefully declining to make any promises about the second half.
Geography is where the story really sits. Europe, up 4.4% overall and 3.7% inside the EU, is carrying the industry right now. France remains the biggest single market, taking some €326 million in frames and sunglasses, though growth there was a barely visible +0.6%. The real energy is elsewhere on the continent: Germany +7.1%, Spain +3.5%, Portugal +13.4%, and Eastern Europe shining brightest - Poland +20.9%, Hungary +10.4%, Croatia +10.5%. The Americas went the other way, down 20.1%, with North America off 24.3%. Asia as a whole slipped 6.0%.
The United States is where the pain concentrates. Italian frame and sunglass exports to the US came to roughly €320 million for the half, down 25.1% - a loss of more than €107 million. ANFAO's own numbers make the point bluntly: strip the US out, and Italian eyewear exports to the rest of the world actually grew. Elsewhere beyond Europe it is a mixed bag - Turkey up 7.8%, Hong Kong up 72.9% on the back of its hub role, but China down 22.8%, Mexico down 20.0% and the UAE down 20.9%.
Back home, Italian optical retail was nearly flat: about €1.8 billion in sell-out, up 0.3% according to NIQ-GfK, which almost counts as good news next to the −2.8% recorded across the major European markets. Lenses, more than half the market by value, rose 1.5%. Frames fell 2.0%. Sunglasses were essentially unmoved at −0.3%. Progressives did the heavy lifting, gaining 2.0% in volume and 2.4% in value, with demand still concentrated in the mid-to-high-end.
Berton's own summary stays cautious. "Market diversification is no longer just an opportunity, but a fundamental component of our companies' competitiveness," she said. The United States remains strategic and will be watched closely; Europe needs to be consolidated; new markets need to be developed.
For European optical buyers and private-label brands, the practical read is simple. Demand is holding in Europe. Italian eyewear makers are absorbing a heavy blow in America and leaning more heavily on their home continent, and that opens room for eyewear manufacturers and private-label suppliers who can put consistent mid-to-premium frames, flexible volumes and genuine design support into European channels - whether to fill gaps while Italian capacity is busy managing the US, or to build private-label eyewear collections that meet European standards and lead times. The second half is anyone's guess. But for now, the steadier business sits on this side of the Atlantic - and someone will have to supply it.
That gap is worth a conversation. Leeyewear is an eyewear manufacturer based in Shenzhen, running OEM and ODM programs across sunglasses, optical frames, blue-light glasses and readers. We work with European private-label buyers on flexible order quantities, stable mid-to-premium quality, and design support from sketch through sampling, with lead times planned around European retail calendars. Certifications and testing are arranged according to each client's requirements and destination market. If your 2027 line-up is still taking shape, the weeks before MIDO are the right time to start sampling.
Sources: Official MIDO and ANFAO materials via Carolina Mailander Comunicazione; ANFAO analysis based on Istat, Euromonitor International and NIQ-GfK for January–June 2026; MIDO registration announcement 25 September 2026.